CNP Meaning: What Is a Card-Not-Present Transaction?
Digital payments are a core part of business, but they come with new risks. Learn what CNP means and how to manage card-not-present transactions.
작성자
 RESOURCE
Retail Store Opening and Closing Checklist
Use this free PDF checklist to set your staff up for success, every shift.
무료 다운로드 받기CNP, or “card not present,” refers to payments where a customer’s physical card isn’t used—like online purchases, phone orders, or invoice payments. As more transactions move online and remote, CNP payments have become a standard part of how businesses get paid.
In fact, card-not-present transactions now account for more than one-third of total transaction volume and nearly half of total value, according to the Federal Reserve.
While they offer convenience and flexibility, they also come with different risks and costs than in-person payments. Understanding how CNP transactions work can help you manage them more effectively and avoid common issues like fraud or chargebacks.
Key takeaways
CNP (card-not-present) transactions are payments where the physical card isn’t used, such as online, phone, or invoice payments.
These transactions are increasingly common and now make up a significant share of total payment volume and value.
CNP payments carry higher risks, including fraud, chargebacks, and increased processing fees.
Businesses can manage CNP transactions more effectively with secure payment systems and built-in safeguards.
Optimizing CNP payment performance is critical, as failed transactions can directly impact customer retention and revenue.
Retail Store Opening Costs Calculator
This free calculator lays out some of the fundamental financial costs of opening a retail store, so you can start planning and bring your dream business to life.
What does CNP mean for businesses?
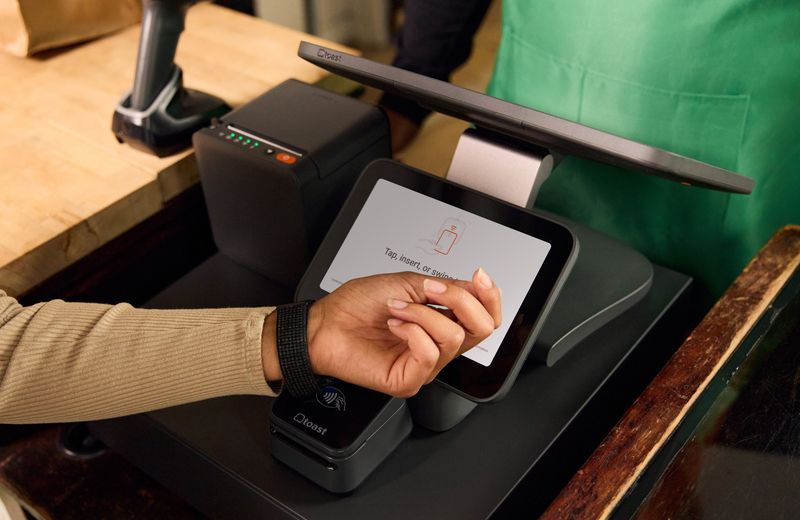
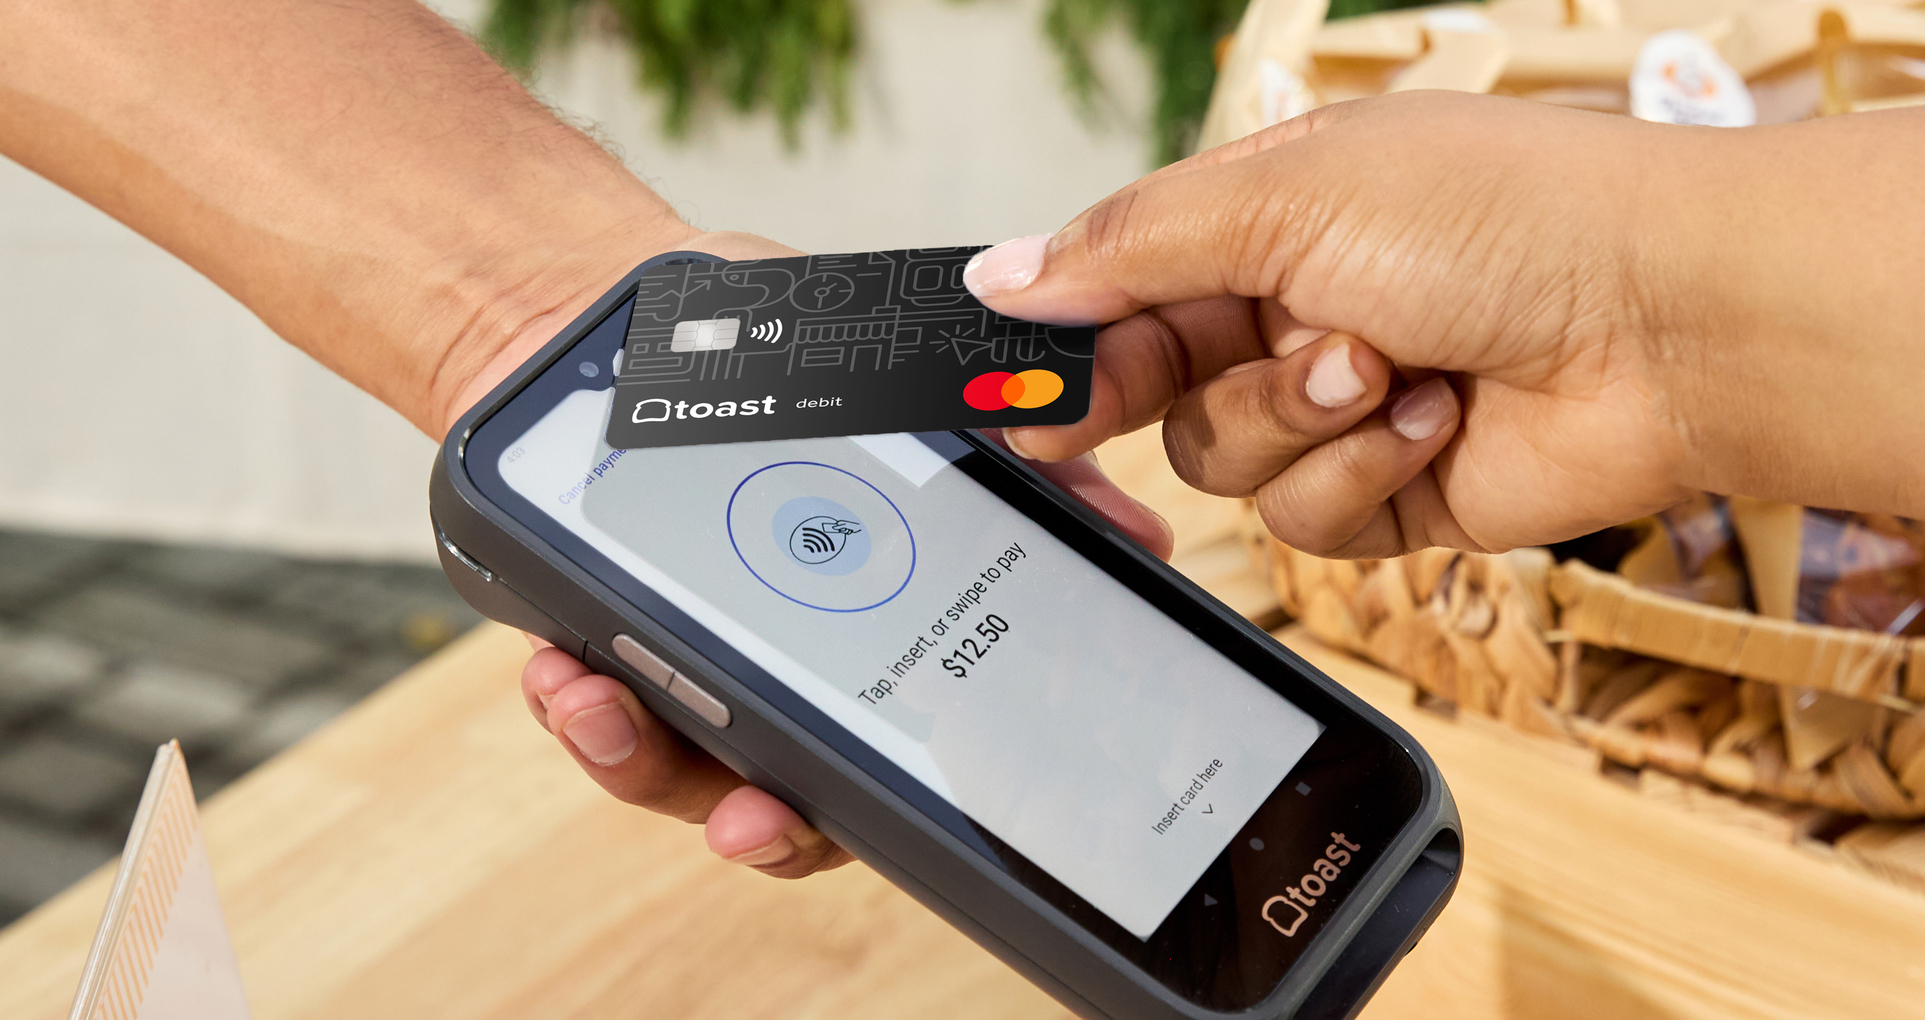
CNP stands for “card not present,” referring to any payment where the customer’s physical card isn’t used during the transaction. Instead of being tapped, inserted, or swiped in person, the payment is processed using card details entered manually or stored digitally.
These transactions are common across many types of businesses, especially as more payments happen online or remotely. Typical examples include:
Online purchases (ecommerce): Customers enter their card details at checkout on a website or app.
Phone or mail orders: Card information is provided verbally or through written forms.
Payment links and invoices: Customers pay by entering their card details through a secure link.
Subscription or recurring payments: Stored card information is used to process ongoing charges automatically.
CNP vs. card-present transactions
The key difference between CNP and card-present transactions comes down to how the payment is processed and the level of risk involved:
How payment is processed: Card-present transactions use a physical card at checkout, while CNP transactions rely on manually entered or stored card details.
Security differences: Card-present payments benefit from in-person verification (like chip or tap), while CNP transactions rely more on digital safeguards.
Fees and risk levels: CNP transactions typically carry higher processing fees and a greater risk of fraud or chargebacks.
Why do CNP transactions matter for businesses?
The number of card-not-present transactions is growing—but they come with different risks and costs than in-person payments.
Recent data highlights the scale of those risks. Breaches have exposed billions of user records, card compromise events in the U.S. rose 8% in 2024, and digital fraud tied to compromised card data has been linked to billions of dollars in preventable losses.
Higher fraud risk: Without a physical card or face-to-face interaction, it’s harder to verify the customer, which can increase the likelihood of fraud.
Increased chargebacks: Disputes are more common with CNP transactions, especially if a customer doesn’t recognize a charge or claims it wasn’t authorized.
Higher processing fees: Payment processors often charge more for CNP transactions to account for the added risk.
Growth of online and remote payments: Ecommerce, delivery, and digital invoicing have made CNP transactions a larger share of overall sales.
Impact on operations and revenue: Managing fraud, disputes, and fees can affect your margins and require more attention to payment processes.
How payment systems help manage CNP transactions
Modern payment systems make it easier to accept and manage card-not-present transactions by bringing security, visibility, and efficiency into one place.
Centralized payment processing: Manage online, phone, and invoice payments from a single system instead of juggling multiple tools.
Secure data handling: Built-in safeguards like encryption, tokenization, and verification checks help protect customer data and reduce fraud risk.
Reporting and analytics: Track sales, payment trends, and chargebacks so you can understand performance and spot potential issues.
Integration with POS and ecommerce: Connect your payment system with your POS, website, or ordering platform to streamline operations and keep everything in sync.
No card, no problem
Card-not-present transactions come with higher risks and costs than in-person payments. But they’re also a normal and growing part of doing business, as customers across all age groups continue to adopt online and remote payments.
That growth is expected to continue, with CNP transactions projected to reach nearly $18 trillion globally by 2030. At the same time, performance matters—40% of customers who experience a decline on their first visit won’t return to a merchant’s site.
The key isn’t to avoid CNP transactions—it’s to manage them effectively. With the right payment system in place, you can accept these payments securely, reduce risk, and deliver a smooth checkout experience that keeps customers coming back.
Purchase Order Template
Use this template to create standardized purchase orders for requesting goods or services from vendors.
FAQ
What does CNP stand for in payments?
CNP stands for “card not present,” meaning the customer’s physical card isn’t used during the transaction, such as with online or phone payments.
Why are CNP transactions riskier than card-present transactions?
CNP transactions are riskier because there’s no physical card or in-person verification, making it harder to confirm the customer’s identity.
Who is liable for CNP fraud?
In most cases, the business (merchant) is responsible for fraud and chargebacks in CNP transactions, especially if the transaction can’t be verified.
What is the difference between CNP and card-present transactions?
CNP transactions are completed without the physical card, while card-present transactions involve a card being tapped, inserted, or swiped in person.
How can a retailer reduce CNP chargebacks?
Retailers can reduce chargebacks by using tools like address verification (AVS), CVV checks, fraud detection systems, and clear refund policies.
Do CNP transactions cost more to process?
Yes, CNP transactions typically have higher processing fees because they carry more risk for payment processors.


이 문서가 도움이 되었나요?
면책 조항: 이 정보는 일반 정보 제공 목적으로 작성되었으며 당사의 권고를 의미하는 것은 아닙니다. Toast는 본 콘텐츠에 포함된 정보, 텍스트, 그래픽, 링크 및 기타 항목의 정확성이나 완전성을 보장하지 않습니다. Toast는 본 문서의 조언을 따른다고 해서 특정한 결과를 얻을 수 있음을 보장하지 않습니다. 귀하의 상황에 맞는 조언이 필요한 경우 변호사, 회계사 또는 비즈니스 자문가 등 전문가와 상담하시기 바랍니다.
 트렌드